Do More Than Pass Go
My wife loves any game or puzzle that requires problem-solving. For years, she has slowly been turning me into someone who enjoys games too.
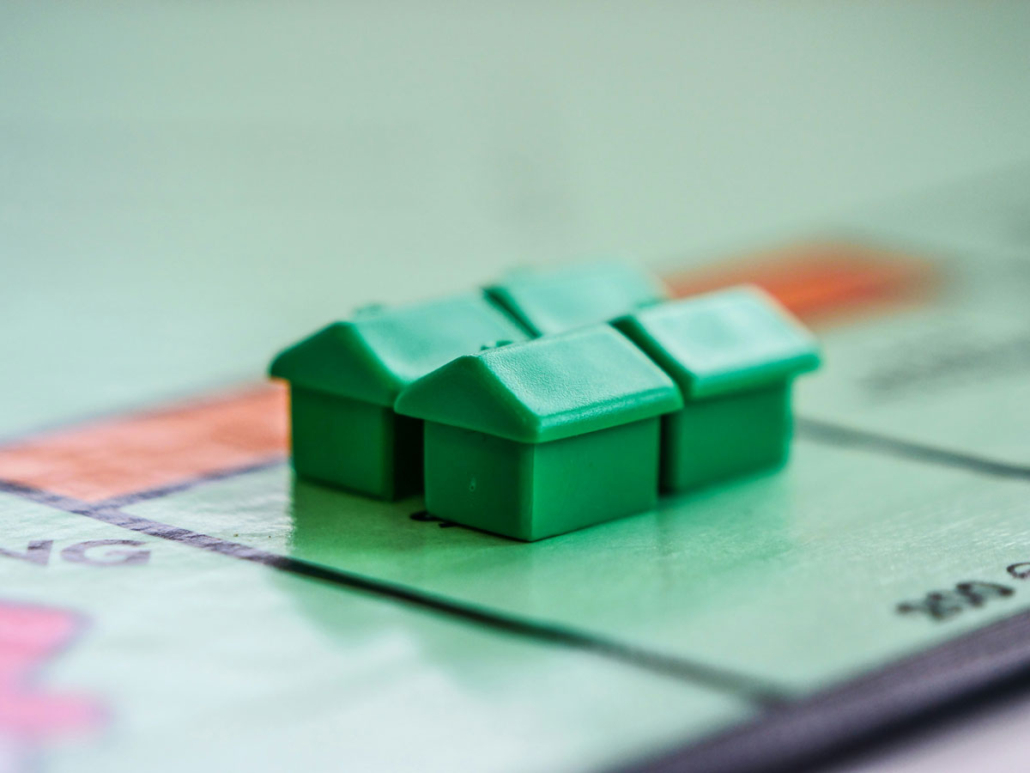
Unsurprisingly, there’s one game I most enjoy: Monopoly.
First released by Parker Brothers in 1935, Monopoly was preceded by “The Landlord’s Game” in the early 1900s. Created by Lizzie Magie, it taught an economic lesson about property ownership, rent and wealth concentration. The game’s details changed over time, and Parker Brothers later popularized the version most families know today, but the basic mechanics remained: Move around the board, acquire property, collect rent and learn quickly that owning productive assets wins out over just collecting cash and paying expenses.
Imagine playing Monopoly but never buying a property. Instead, you simply advance your token, collect $200 when you pass GO, pay rent and try to evade jail. It sounds ridiculous, yet that is how many people approach their financial lives.
I think a useful investing lesson is hidden inside that cardboard box.
During our working lives, we go around the board, collecting our version of $200 as a paycheck. We follow the rules, get educated, build a career, work hard, raise families, buy homes, take vacations, pay bills and hopefully invest some of our earnings. We follow this cycle on repeat.
There’s nothing wrong with that. Work is productive and honorable, and earned income provides for us and those we love. But somewhere during those forty-something working years, an important transition must occur. We must shift from thinking about how much money we earn to how much our money can earn for us.
That’s where ownership of assets enters.
In Monopoly, purchasing properties requires shelling out cash. And if cash alone could determine a winner, each purchase might feel like a step backward. Your pile of money shrunk, and all you’re left with is a beat-up Baltic Avenue. But cash value doesn’t fully capture the wealth produced by a productive asset. When other players land on your property, they must pay you rent. As you acquire and improve your properties, you get more substantial income each time an opponent gets unlucky with their dice roll. Eventually, the weakest player is pleading to pass GO without landing on any opponents’ properties.
Investing in real businesses works differently, but the principle remains. A share of stock is not just a symbol moving on a screen. It’s ownership in an actual business. Behind every ticker are employees at work, customers buying products and services, and management teams trying to increase the value of the enterprise.
This is where the Monopoly analogy becomes especially helpful. Imagine you’ve played the game well, and now own both Boardwalk and Park Place. You’ve even picked up a few houses, converting those assets into substantial income when others land on them.
But imagine deciding that whenever you need money, you will just sell one of those properties.
You can certainly do that, just as retirees can sell investments to support spending. But if selling becomes your primary strategy, you sacrifice the very economic engine you spent the entire game building. That’s why I’ve long advocated for owning successful businesses that return a portion of their profits to shareholders. A dividend is not magic money, but it’s a way of sharing business income among owners.
Keep in mind, a higher dividend yield, while desirable, may not tell the whole story. In Monopoly, it’s not enough to own a hotel on Boardwalk if everyone manages to avoid landing on it. An asset’s actual income matters more than its appearance. In business ownership, that means prioritizing profitability, balance-sheet strength, management, competitive advantage and whether the dividend is supported by durable earnings and cash flow.
There’s one other behavioral element tied to this Monopoly analogy. Imagine if a digital screen beside the game board repriced properties after every roll of the dice. Boardwalk down 12%. Railroads up 8%. Park Place down 15% because someone panicked about interest rates.
Would these changing prices alter why you bought those properties? Probably not. Yet this is exactly what investors experience every business day. We receive constantly updated prices for our ownership interests, and we prioritize those prices as critical.
The market tells us what someone is willing to pay for ownership today. The business tells us what our ownership is producing.
That distinction can dramatically improve investor behavior during difficult markets. Imagine a year when your portfolio temporarily declines in price, but the businesses you own collectively increase their dividends. The market value is lower, but your income went up. Which matters more?
The answer depends on your time horizon and plan. If you must sell everything tomorrow, today’s price matters enormously. But if you’re a long-term owner seeking to fund a multi-decade retirement, temporary price changes may matter less than the continuing productivity of your assets.
Given enough time, those assets may produce meaningful income of their own. Eventually, another trip around the board may become optional.
That, to me, is a description of financial independence. Rather than simply having a large account balance, it means owning enough productive assets that they can support your desired life.
Beneath the dice, colorful money and little metal pieces is a remarkably important lesson about money. Income moves you around the board, but ownership is how you win the game.
Steve Booren is the Owner and Founder of Prosperion Financial Advisors, located in Greenwood Village, Colo. He is the author of Blind Spots: The Mental Mistakes Investors Make and Intelligent Investing: Your Guide to a Growing Retirement Income and a regular columnist in The Denver Post. He was recently named a Barron’s Top Financial Advisor and recognized as a Forbes Top Wealth Advisor in Colorado.